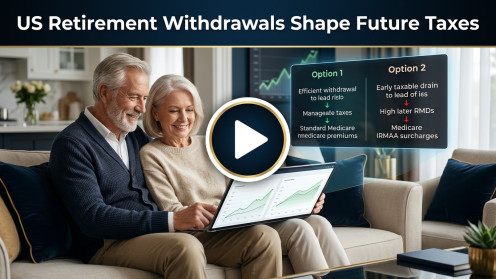
After years of serving and protecting families, I’ve seen firsthand how financial decisions—especially around retirement withdrawals—shape our future security. It’s remarkable how two retirees with identical $2.1M portfolios can end up with very different tax outcomes, all because of the paths they chose early on. For example, how you split your assets between taxable accounts and a traditional IRA impacts not just your current income (like that $117,400 per year scenario), but also how much you’ll owe in taxes and Medicare surcharges down the line.
For joint filers in 2026, keeping your MAGI at or below $218,000 means you’ll pay standard Medicare premiums. Go just one dollar over, and your Part B premiums can jump by nearly $284, plus Part D surcharges. It’s a reminder that every little decision counts. Draining taxable accounts first might let your IRA grow, but it also sets you up for larger required minimum distributions (RMDs) later—potentially pushing you into higher tax brackets and higher Medicare costs. On the other hand, planning IRA withdrawals or conversions before you hit RMD age could help you avoid future pressure.
As a financial coach, I encourage families to model their RMD paths before year’s end, keep Roth conversions below the next IRMAA threshold, and regularly review IRA holdings for risks like floating rates, leverage, and concentration. These are the steps that help build lasting security and empower families to protect what matters most for generations to come.
Leave a Reply