Blog

  • Easy Financial Planning Tips for Seniors

    Easy Financial Planning Tips for Seniors

    After years devoted to protecting my community, I now focus on helping families safeguard their financial well-being—especially as they approach their golden years. I know firsthand how vital it is to prepare for the future, not just for yourself but for those who rely on you. For seniors, a few practical steps can make a big difference: set clear financial goals, establish a budget that includes an emergency fund, regularly review care needs, make thoughtful investment choices, select the right insurance coverage, plan your estate, and take advantage of support programs available to you. These strategies aren’t just about numbers—they’re about creating peace of mind and ensuring your legacy endures. My mission is to empower you with the financial knowledge and tools you need to protect what matters most.

    Continue to full article

  • Retirement Wealth Needs a Preservation Plan

    Retirement Wealth Needs a Preservation Plan

    After two decades of serving my community—as a U.S. Army Veteran, police officer, and now as a Financial Coach—I’ve seen firsthand how crucial it is to protect what matters most. Preserving your retirement savings is no different. Recent research shows that Americans are aiming for about $1.5 million to retire comfortably, while those with greater resources set their sights closer to $2.7 million. Even with larger nest eggs, the need for a sound preservation plan doesn't go away.

    For example, following the widely used 4% withdrawal rule, a $2 million portfolio might provide around $80,000 per year. But factors like lifestyle, where you live, taxes, healthcare costs, and how long you’ll need your money can impact that number more than many expect. Large IRA and 401(k) balances can also trigger significant tax consequences in retirement, so it’s wise to plan withdrawals carefully and consider options like Roth conversions to help preserve your income.

    Many experts suggest a balanced portfolio—about 50% in public equities, 28% in private or alternative investments, and 10% in bonds and cash—to help weather market ups and downs. While exotic investment vehicles can sometimes seem appealing, they often come with limited liquidity. For most retirees, simple index funds, bond funds, and thoughtful estate planning provide both stability and peace of mind, especially since many Americans still don’t have a will in place.

    My mission now is to empower families to make informed decisions, safeguard their hard-earned savings, and build a legacy for those they love. Protecting your financial future starts with a plan—one designed to stand the test of time.
  • US Retirement Withdrawals Shape Future Taxes

    US Retirement Withdrawals Shape Future Taxes

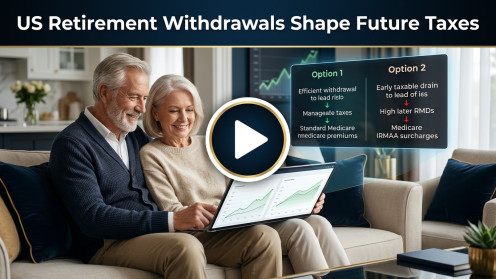
    After years of serving and protecting families, I’ve seen firsthand how financial decisions—especially around retirement withdrawals—shape our future security. It’s remarkable how two retirees with identical $2.1M portfolios can end up with very different tax outcomes, all because of the paths they chose early on. For example, how you split your assets between taxable accounts and a traditional IRA impacts not just your current income (like that $117,400 per year scenario), but also how much you’ll owe in taxes and Medicare surcharges down the line.

    For joint filers in 2026, keeping your MAGI at or below $218,000 means you’ll pay standard Medicare premiums. Go just one dollar over, and your Part B premiums can jump by nearly $284, plus Part D surcharges. It’s a reminder that every little decision counts. Draining taxable accounts first might let your IRA grow, but it also sets you up for larger required minimum distributions (RMDs) later—potentially pushing you into higher tax brackets and higher Medicare costs. On the other hand, planning IRA withdrawals or conversions before you hit RMD age could help you avoid future pressure.

    As a financial coach, I encourage families to model their RMD paths before year’s end, keep Roth conversions below the next IRMAA threshold, and regularly review IRA holdings for risks like floating rates, leverage, and concentration. These are the steps that help build lasting security and empower families to protect what matters most for generations to come.

  • How HSAs Fit Into Retirement Planning

    How HSAs Fit Into Retirement Planning

    After years of serving and protecting others, I’ve seen firsthand how important it is to secure your family’s future—both today and for the years ahead. One tool that often flies under the radar is the Health Savings Account (HSA). For those with high-deductible health plans, HSAs offer a rare triple tax advantage: pretax contributions, tax-free growth, and tax-free withdrawals for qualified medical expenses. Unlike some accounts, your HSA balance rolls over year after year and stays with you, even if you change jobs—making it a flexible resource for covering deductibles and out-of-pocket medical costs.

    What many families may not realize is that, with a thoughtful approach, an HSA can be more than just a rainy-day fund for healthcare. By investing your HSA balance instead of spending it down each year, you’re adding another layer to your long-term retirement strategy—one that can provide added security as you look to the future.

    Estate planning matters here, too. Be sure to review and update your HSA beneficiary designations, especially after big life changes. A will isn’t always enough to cover every account, so weaving your HSA into your broader retirement and estate plans can help ensure your wishes are honored. Ultimately, every step you take today builds the legacy you’ll leave for tomorrow.

  • What No One Tells You About Retiring Alone

    What No One Tells You About Retiring Alone

    Retiring solo is a path with unique rewards and challenges. Many single retirees value their independence, yet the financial landscape can feel more uncertain when you’re relying on one Social Security benefit. After years spent in service and later as a financial coach, I’ve seen firsthand how important it is to plan ahead—especially when you’re on your own. Having larger savings, a thoughtful long-term care plan, solid estate planning, and nurturing social connections are all critical pieces for a secure, meaningful retirement. Empowering individuals to make informed decisions and build lasting security has become my mission. No matter your situation, it’s never too early—or too late—to build the foundation for a fulfilling retirement and create a legacy for those you care about.

    Continue to full article

  • IRA vs. 401(k): How to Prioritize

    IRA vs. 401(k): How to Prioritize

    Having spent decades protecting families and serving my community, I know how important it is to make smart decisions that safeguard your financial future. When it comes to retirement planning, many people ask whether to prioritize contributions to an IRA or a 401(k). Here’s a practical approach I often recommend: first, contribute to your 401(k) up to the amount your employer will match—never leave that free money on the table. Next, consider maximizing an IRA, which can offer broader investment choices and potentially lower fees. After that, any additional retirement savings can go back into your 401(k). For those who earn above income limits, strategies like the backdoor Roth IRA can be valuable. Finally, deciding between a traditional or Roth account? Let your future tax expectations guide you. My goal is to help families use every available tool to create lasting security and build a legacy for the next generation.

    Continue to full article

  • How Annuity Agents Grow Financial Confidence

    How Annuity Agents Grow Financial Confidence

    After spending over two decades serving my community in the U.S. Army and law enforcement, I learned firsthand how crucial it is to safeguard what matters most—our families and our futures. That same drive now fuels my work as a Financial Coach. One of the most powerful ways I help families is by guiding them through the world of annuities. I believe that true financial confidence starts with understanding your options. My approach is to walk clients through the different types of annuities, carefully assessing their unique needs, and recommending solutions that align with their goals. I make it a priority to explain the details in plain language and provide ongoing support, so every family I work with can make informed decisions and move closer to lasting financial security. For me, it’s all about empowering you to protect your loved ones and build a legacy that lasts.

    Continue to full article

  • Prevent Ex-Spouse From Inheriting Assets

    Prevent Ex-Spouse From Inheriting Assets

    Having spent my career protecting families—in uniform and now as a financial coach—I know just how crucial it is to make sure your assets end up where you intend, especially after life changes like divorce. Many people don't realize that while a finalized divorce can automatically revoke gifts or roles for an ex-spouse in your will, that safeguard typically doesn't apply during a pending separation. Your will only covers assets in your name without a designated beneficiary, but things like retirement accounts, bank accounts, annuities, pensions, and life insurance often pass outside probate. If beneficiary forms aren’t updated after a divorce, these assets could go directly to an ex-spouse, regardless of your will. Living trusts can offer more control, skip probate, and help manage assets if you’re ever incapacitated, but these also need to be reviewed and updated after a divorce. Always read your divorce orders closely—sometimes, you may be required to keep an ex as a beneficiary, and some employer plans are governed by federal rules. Once your divorce is finalized, make it a priority to update your will, beneficiary forms, and trusts. Consulting with an attorney can help ensure your assets are protected and passed on in line with your wishes. Empowering families to make informed decisions is what I’m here for—protect what matters most, for today and for generations to come.

  • How Much Dividend Income Can You Buy?

    How Much Dividend Income Can You Buy?

    After years spent protecting people and serving my community, I’ve learned that safeguarding your financial future is just as important as physical security. Many families ask me: what kind of retirement income can you expect from dividend investments—say, with a $250,000 rollover? The answer depends on several factors: the specific holdings you select, your account type, the dividend yield, payout coverage, and even how often those dividends are paid.

    In my own analysis, I focus on IRA-friendly options, steering clear of investments that bring extra tax headaches like K-1 forms or UBTI—so I stick mostly to dividend-paying corporations and the occasional REIT. With a Treasury yield around 5% as our benchmark, only the REIT in this mix surpassed that yield, but remember: high yield alone isn’t the full story. We have to consider risks like leverage, tenant quality, fluctuating commodities, and even industry-specific issues like cigarette volumes or patent disputes. That’s why I prioritize coverage and sustainability, pairing monthly and quarterly payouts from companies with strong dividend growth histories and solid earnings guidance.

    For retirees hoping to live on dividends, this strategy can help reduce the need to sell investments during market downturns. Still, the tax treatment and reliability of these payouts are crucial—so I always suggest working with a professional to make sure your plan is built to last. My mission is to empower you to make informed choices, protect your income, and build a legacy for your loved ones.

  • Essential Tips for Retirement Planning

    Essential Tips for Retirement Planning

    After years of serving my community and protecting families, I’ve seen firsthand how critical it is to plan for the years ahead—especially when it comes to retirement. For those thinking about their next chapter, remember: it’s not just about growing your nest egg, but making sure your money lasts a lifetime. Rather than sticking to rigid spending rules, consider adjusting your withdrawals based on how the markets are performing. Keeping a cash reserve can also give you peace of mind and help you avoid selling investments during downturns. It’s important to maintain some growth in your portfolio to stay ahead of inflation, all while planning your withdrawals in a way that could reduce your tax burden. And don’t overlook guaranteed income sources like Social Security to cover essential living and healthcare expenses. My goal is to empower you with strategies that help you protect what matters most—your family’s future and your financial security.